
 Buy now, Pay later

What Credit Score Do You Need for Bed Finance? A 2026 Guide
What if the credit score you’re worried about isn’t the only thing a bed finance provider considers? There’s no single score that guarantees acceptance, so wondering what credit score for bed finance you need doesn’t have to mean ruling yourself out before you understand the options.
It’s sensible to consider eligibility and whether an application could affect your credit file. The answer can depend on the lender, the type of finance and the wider details in your credit history. A hard check and a soft check can have different effects, so check which type may apply before proceeding.
In this guide, we’ll explain what providers may consider, what to review on your credit report and how to compare repayment terms. We’ll also explain how we use Klarna to provide interest free payments for amounts up to £1000, spread over 3 months. With a clearer picture of your options, you can consider a comfortable bed and a payment plan with greater confidence.
Key Takeaways
- There’s no guaranteed threshold for what credit score for bed finance will secure approval. A score is just one indicator of your credit file.
- Look beyond the number: payment history, existing commitments and the details on your application may also matter.
- Compare paying upfront, using savings and spreading payments by considering timing, repayment commitments and what fits your budget.
- Before applying, review your credit file and personal details, set a budget, and make sure you understand the repayments and Klarna’s current terms.
What credit score do you need for bed finance?
There’s no universal credit score that guarantees approval for bed finance. A score is an indicator based on information in your credit file, not a pass mark that every provider uses in the same way. The answer to “what credit score for bed finance?” depends on the provider’s criteria and assessment process, as well as the information available when you apply.
This can feel uncertain if you’ve seen a particular number described as the score you need. Treat a score as a guide to your credit history, not a promise of acceptance or refusal. Each provider makes its own eligibility decision, and different providers may reach different outcomes.
Does a particular credit score guarantee acceptance?
No. A score by itself can’t predict every provider’s decision. Finance providers may use different criteria and assess information in different ways, so a score that appears acceptable in one place won’t guarantee approval elsewhere. Equally, a lower score on a credit-checking service doesn’t tell you exactly how a specific provider will decide. Don’t treat any one number as universally good, poor or sufficient for bed finance.
What is the difference between a credit score and a credit file?
Your credit file is the underlying record of credit-related information about you. A credit score is a number calculated from information in that record. The Credit score overview explains the general purpose of scores, but the number you see is only a summary, not your full file or a lender’s final decision.
Credit reference agencies may display different scores because they can use different scales or ways of presenting information. That doesn’t mean one agency controls whether you’re accepted. A finance provider may assess information from a credit reference agency alongside its own criteria, and the score shown to you may not be the exact figure or method used in its decision.
It helps to separate three things: the information recorded about you, the score a service calculates from it, and the provider’s eligibility decision. They’re connected, but they aren’t interchangeable. If a displayed score changes, it doesn’t automatically mean every provider will make the same assessment or that your eligibility has changed in the same way.
Use your score as a prompt to understand your credit history, not as a verdict. Focus on the details behind the number and remember that each provider sets its own criteria. Next, consider what information a provider may look at beyond the score itself.
What can affect a bed finance application besides your score?
A displayed score is only part of the picture. A finance provider may also consider information in your credit history, your current commitments and the details you provide on an application. These factors offer context, but they don’t let anyone outside the provider reliably predict the result. Understanding what credit score for bed finance means in practice involves looking at the wider information behind the number.
For example, a credit file might show a history of payments alongside current borrowing. Your application may also include details the provider uses to understand the request. Enter information accurately and check it against your records. A difference in an address or another personal detail doesn’t automatically mean an application will be declined, but checking details can help avoid preventable confusion.
- Payment history: Your file may include records of whether payments were made on time. Providers may consider this as part of your broader credit history.
- Existing commitments: Other regular credit repayments can provide context about your finances and the commitments you already manage.
- Application details: The information you submit, including personal details and the finance requested, may form part of the provider’s assessment.
How might credit history differ from the score shown?
Your credit file contains the underlying records, while a score summarises some of that information. In the UK, Experian, Equifax and TransUnion are credit reference agencies, and the scores or formats they show may differ. Review your personal details and account information on the report available to you. If something looks inaccurate, contact the relevant agency and follow its process for raising a correction.
Check carefully for details such as an old address or an account entry you don’t recognise. Note what seems wrong and any steps you take to query it. This gives you a clearer view of your records before applying, without assuming that a score from one agency is the same as the provider’s own assessment.
Why might affordability matter to a finance provider?
Affordability, in everyday terms, is whether repayments appear manageable alongside your regular outgoings and other credit commitments. A provider may consider existing commitments as context, but only that provider can explain how its own criteria apply. Don’t rely on a displayed score alone to judge whether repayments will fit your budget.
Before submitting an application, work out what repayment amount would feel manageable after essential bills and other regular costs. Consider possible changes to your monthly budget, too. Approval depends on the provider’s assessment. The factors described here are general guidance, not a statement of how Klarna or any other specific provider assesses an application.
Once you have a clearer budget, browse beds and mattresses from Belfast Bed Superstore, serving customers in Cambridge and across Cambridgeshire and East Anglia.
How should you compare bed finance with other payment options?
A comfortable bed should also feel manageable for your household budget. Paying upfront, using savings or choosing instalments each affects your money differently, so compare the timing and commitment before deciding. This holds true whether you are upgrading your main bedroom or planning for a new arrival with convertible nursery cribs from BabyRace. The right choice depends on your circumstances, not on what someone else might choose or on the answer to “what credit score for bed finance?”
| Payment option | Payment timing | Repayment commitment | Questions to consider |
|---|---|---|---|
| Paying upfront | The full amount is paid at purchase. | No instalments remain for that purchase. | Have you budgeted for the full amount while keeping enough available for household costs? |
| Using available savings | You use money set aside before buying. | There are no repayments to a finance provider, but your savings balance will be lower. | Would using these savings leave enough for planned expenses or unexpected needs? |
| Choosing instalments | Payments are made over the schedule set out in the agreement. | You’re responsible for making each agreed repayment. | Do you understand the payment dates, amounts, terms and any conditions? |
What should you understand before choosing instalments?
Read the payment schedule before proceeding. Make sure you know the amount and date of each repayment, how long the schedule lasts and what terms apply. Interest free payments still involve an agreement and require repayments to be manageable. Interest free doesn’t mean you can overlook the conditions or payment dates.
We use Klarna to provide interest free payments to customers. Before choosing this option, review Klarna’s current terms and consider whether each repayment fits alongside regular household costs, such as bills and other commitments. A simple budget can help: note your usual outgoings, then check whether the planned payment leaves enough for everyday needs. If the figures feel tight, pause and consider another route.
When might paying upfront suit your circumstances better?
Paying upfront may suit you if you’ve budgeted for the full purchase and can pay without putting pressure on essential spending. The payment is made at the time of purchase rather than spread across future dates. Using savings is another way to pay upfront, but consider what those funds were set aside for before using them.
Instalments can spread payments over time, but they also create a commitment to follow the agreed schedule. Neither approach is automatically better. Think about your current budget, upcoming household costs and how much financial flexibility you want to keep. Choose the option that feels clear and sustainable for you, then browse our bed and mattress range.
What can you do before applying for bed finance?
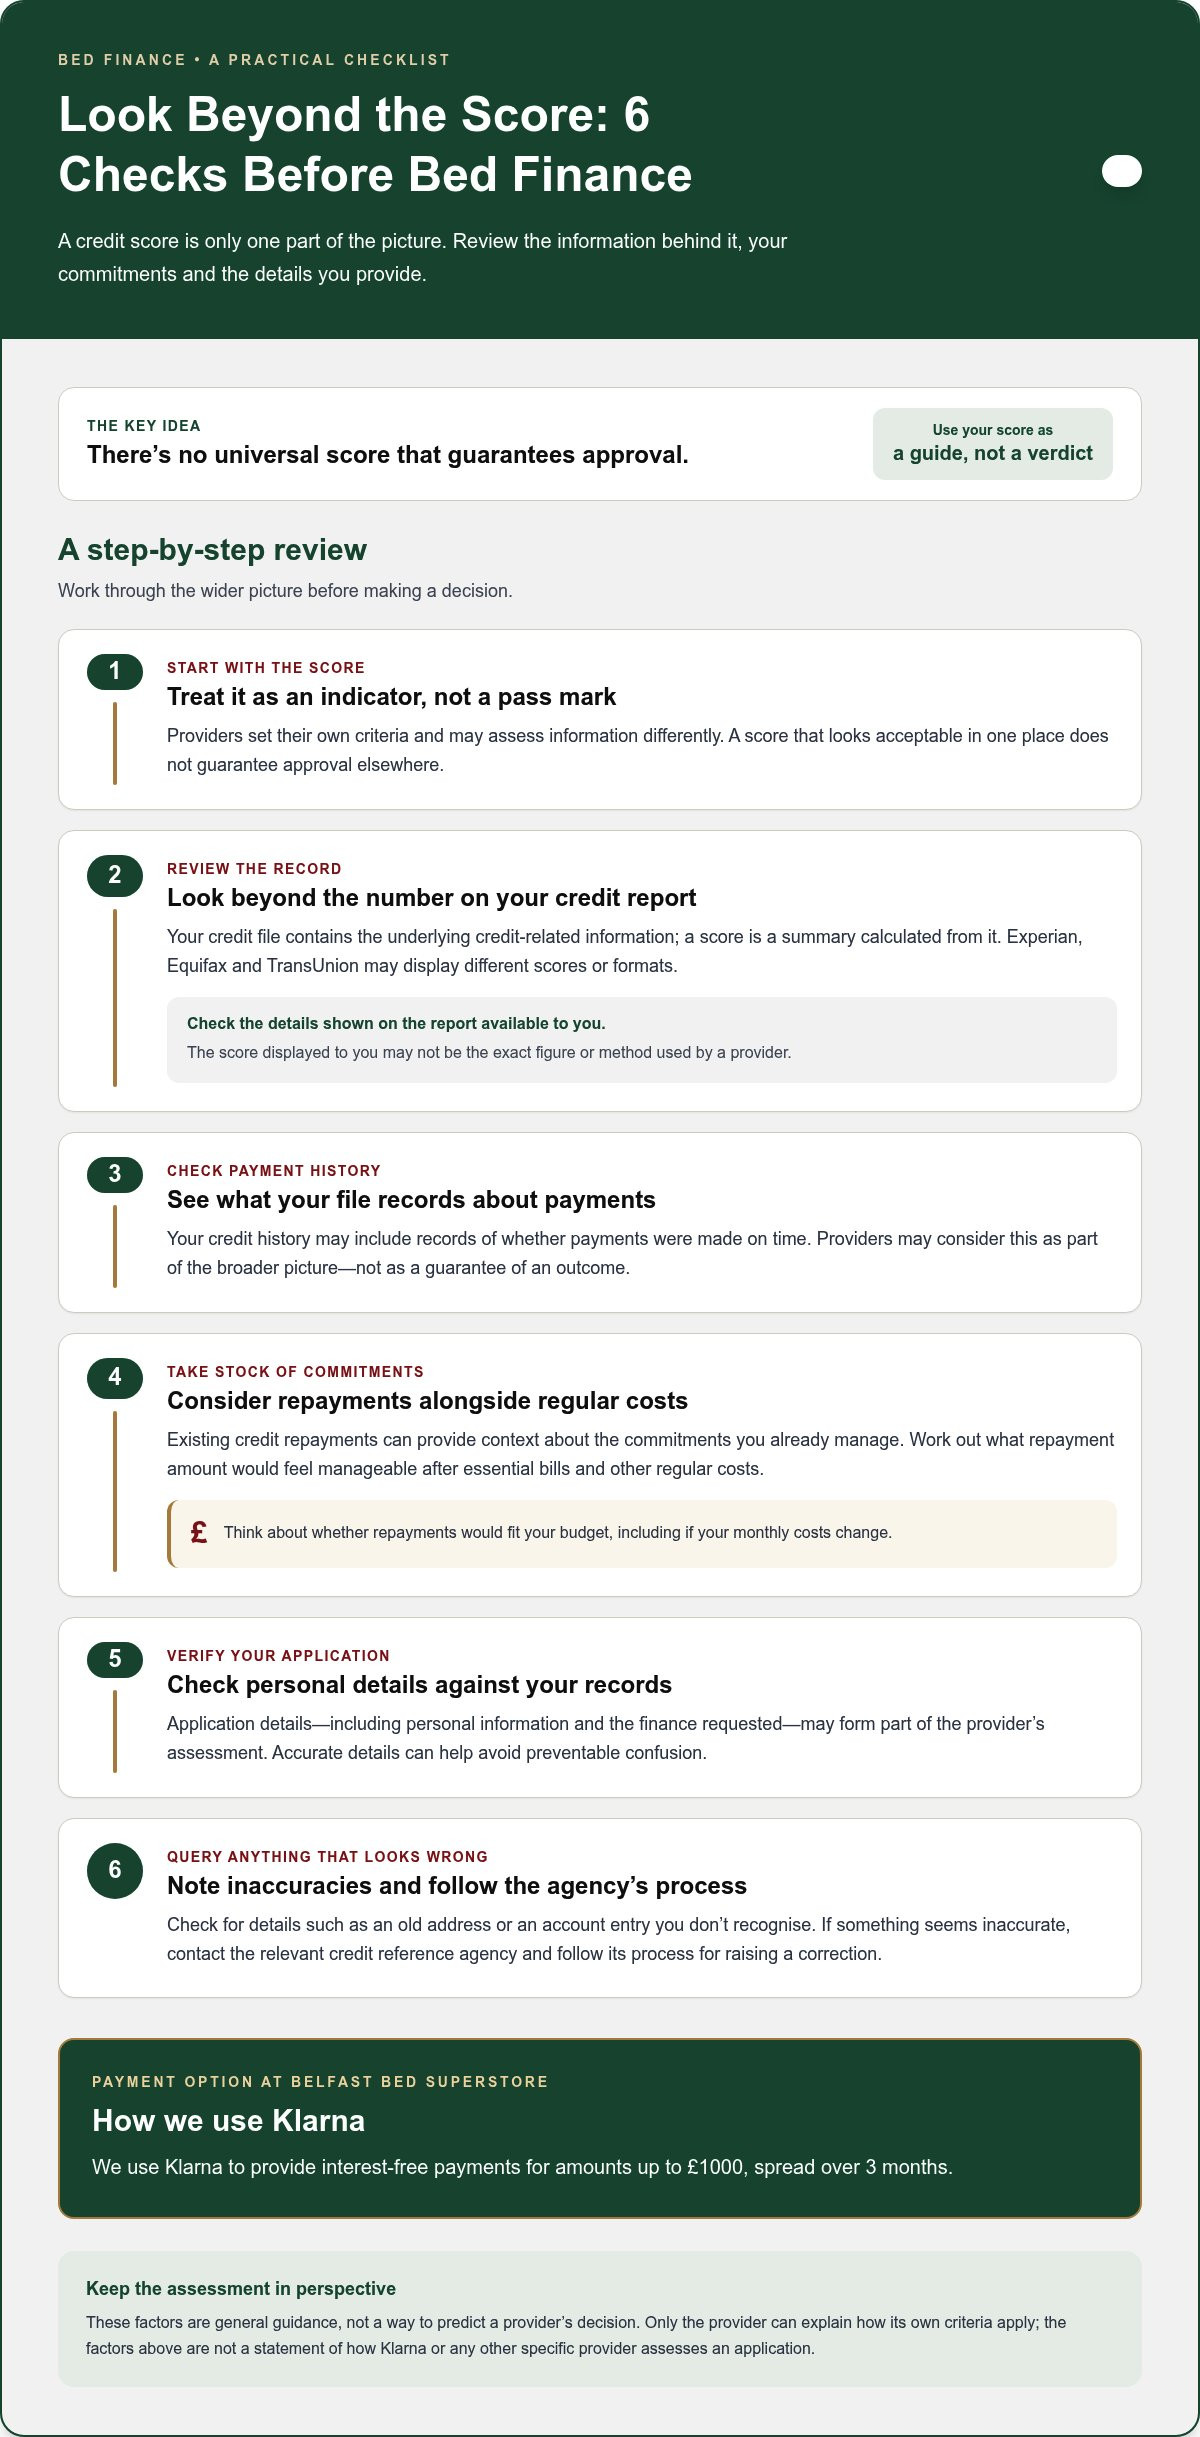
A little preparation can help you understand your finances and the agreement before you apply. It can’t guarantee approval or change a provider’s decision, but it can help you spot errors, set a realistic spending limit and avoid agreeing to repayments that don’t suit your household budget. If you’re considering what credit score for bed finance might mean for your application, focus on these practical steps as well as the number.
Use this short checklist before completing an application:
- Review your credit file: Check that your personal details and account information look accurate.
- Set a budget: Decide what you could comfortably repay while covering your usual household costs.
- Understand the repayments: Read the schedule and current terms so you know the amount, dates and conditions before proceeding.
How can you review your credit information first?
Look at the information held about you by a UK credit reference agency. Check that your name, current and previous addresses, and account details are correct. A score gives only a summary, so review the records behind it, including accounts you may have forgotten about or details that appear unfamiliar.
If an entry seems inaccurate, contact the relevant agency and follow its process for querying or correcting the information. Keep a note of the item you’ve raised and any response. Correcting an error can make your file more accurate, but it doesn’t guarantee a finance application outcome. A provider still makes its own decision using its criteria and assessment.
What should you work out in your budget?
Choose a repayment amount that feels comfortable before settling on a bed or payment method. Start with take-home income and regular commitments, such as household bills, food, travel and existing repayments. Then consider what remains, rather than basing your decision on the maximum amount you might be offered. Don’t borrow more than you can manage.
Leave some room for costs that can vary from month to month, as well as changes you can reasonably anticipate. A repayment that looks manageable on paper may feel different if an essential bill rises or another expense comes up. If your budget is already stretched, reconsider the amount or timing rather than relying on future circumstances to make the payments work.
Before you submit anything, read the provider’s current terms and make sure the repayment schedule matches your understanding. Check the conditions and payment dates, and make sure you understand what you’re agreeing to. Preparation helps you make an informed choice, but it isn’t a promise of acceptance. Once your budget is clear, browse beds and mattresses with your comfort and planned repayments in mind.
How Klarna bed finance works at Belfast Bed Superstore
A payment option is most helpful when its limits and commitment are clear before you decide. We use Klarna to provide interest free payments to customers for amounts up to £1000, spread over 3 months. This gives you a defined option to consider alongside paying upfront or using savings, while keeping your budget and comfort in view.
What are the stated Klarna payment terms?
The payments are interest free, for amounts up to £1000, spread over 3 months. Before proceeding, review Klarna’s current terms so you understand the agreement and what you’ll be committing to. Read the details presented during the application, which explain the terms that apply to you. Don’t assume that interest free means there are no conditions or that an application will automatically be accepted.
You’ll need to complete Klarna’s assessment as part of considering the payment option. Eligibility is assessed individually, and approval isn’t guaranteed. A credit score on its own can’t confirm the outcome, so there’s no particular score we can present as a promise of acceptance. The assessment and current terms matter to your application.
What is a sensible next step if you are considering bed finance?
Start with the bed that suits your needs, then check that its cost and the associated repayments fit comfortably within your budget. Think about the full repayment commitment, not just whether the first payment seems manageable. Leave room for regular household bills and other costs, and don’t choose a payment plan that depends on stretching your budget too far.
Before you submit an application, read the current terms and make sure you understand the repayment arrangement. If anything is unclear, pause and review the information available in the application process rather than guessing. This gives you a clearer basis for deciding whether to continue. Applying is your choice, and taking time to consider the commitment is a sensible part of it.
Questions about what credit score for bed finance might mean are understandable, but a score can’t guarantee an individual result. Klarna’s assessment determines eligibility for its option, so consider it only after reviewing the terms and checking that the repayments fit your circumstances. You can explore our beds at your own pace and compare them with the comfort and support you’re looking for.
Explore beds at Belfast Bed Superstore
Choose a bed and payment plan that feel right for you
Your next step can be simple: decide what comfort and support you need, then use your budget to guide your choices. The question of what credit score for bed finance doesn’t have a single answer, so there’s no need to decide based on a score alone. Take time to understand any payment commitment before applying, and choose only what feels manageable for your circumstances.
As an independent, family-run specialist retailer established in 1990, we’re here to help you explore beds and payment options at your own pace. Our Klarna option is one route to consider as you compare what suits your home and budget.
Explore beds and payment options and take the next step towards a more comfortable night’s rest with confidence.
Frequently Asked Questions
What credit score do I need to get bed finance?
There isn’t one score that guarantees bed finance approval. If you’re wondering what credit score for bed finance will be enough, remember that a provider makes its own decision using its assessment criteria. For example, a score shown by a credit-checking service may not match how a provider views your application. Focus on understanding your credit information and the terms offered rather than aiming for a single universal number.
Can I get bed finance with a poor credit score?
It may still be possible, but a lower score doesn’t guarantee either acceptance or refusal. Each provider assesses applications individually, and its decision can depend on more than the score displayed to you. Before applying, check your credit file for details you can query and consider whether repayments fit your budget. Avoid submitting applications just to find out what you might be offered, as checks and outcomes can vary.
Does applying for bed finance affect my credit score?
It depends on the type of credit check involved. A soft check generally doesn’t affect your score, while a hard check can be recorded on your credit file and may affect it. The application information should explain what kind of check is used. Read it before proceeding, and avoid making several credit applications close together without first considering their possible effect on your file.
What happens if my bed finance application is declined?
A declined application means that provider hasn’t approved that request. It doesn’t automatically determine the outcome of every future application. Pause before applying elsewhere. Review any information provided about the decision, check your credit file for details that may need correcting, and revisit your budget. If circumstances or records change, you can decide whether applying again is right for you.
Can I use Klarna to pay for a bed interest free?
Yes. We use Klarna to provide interest free payments to customers, subject to Klarna’s assessment and current terms. Before choosing this option, read the information shown during the application so you understand the agreement and repayment commitment. Interest free describes the payment option, but it doesn’t mean approval is automatic. Consider whether the payments fit comfortably alongside your usual household spending before proceeding.
How much can I pay through Klarna, and over what period?
We use Klarna to provide interest free payments for amounts up to £1000, spread over 3 months. Review Klarna’s current terms and the details presented during its assessment before completing an application. These stated limits don’t guarantee eligibility for an individual purchase or applicant. Check that the repayment commitment works with your budget, including other planned costs, before deciding whether to use this payment option.
Is bed finance guaranteed if I meet the payment terms?
No, meeting or intending to meet a payment schedule doesn’t guarantee approval. A finance provider assesses the application, and eligibility is decided individually. For a Klarna application, complete its assessment and read the current terms rather than relying on a credit score or assumptions about acceptance. Shoppers in Cambridge and across Cambridgeshire and East Anglia can compare beds at a comfortable pace, then consider payment choices within their budget.