
 Buy now, Pay later

Can You Finance a Mattress Purchase? Payment Options
Yes, you can finance a mattress purchase and spread the cost instead of paying for it all at once. We use Klarna to provide interest free payments on amounts up to £1000, spread over 3 months. It’s a straightforward way to consider a new mattress while keeping the payment plan in view.
It’s sensible to look at the terms before choosing how to pay, especially if you’re wondering about 0% APR eligibility, credit checks or applying with bad credit. This guide explains the payment options, what to expect from the application process and how minimum order values can affect finance. You’ll have a clearer picture of the details to weigh up before deciding which option suits your budget.
Key Takeaways
- We use Klarna to provide interest free payments on amounts up to £1000, spread over 3 months.
- Learn what to expect when applying at checkout and how a credit assessment can affect the decision.
- See how repayment examples can differ between interest-free and interest-bearing finance.
- Explore mattress and mattress-protector options to help choose what suits your comfort needs.
Do you offer finance or pay later options?
Yes. We use Klarna to provide interest free payments on amounts up to £1000, spread over 3 months. This option breaks the eligible purchase into payments rather than requiring the full amount at checkout. The available payment method and terms should be clear during checkout, before you accept an agreement.
Interest-free credit is subject to an application decision. A lender may assess information such as your identity, credit history, income, employment and existing financial commitments. Having a job or using a particular payment method does not, by itself, guarantee approval. The Financial Conduct Authority is named in finance disclosures, but an application decision is based on the applicant’s circumstances and the lender’s criteria.
Minimum spend matters too. This threshold is distinct from our Klarna offer, which applies to amounts up to £1000. Check the amount being financed, rather than only the order total, when reviewing a payment plan.
V12 Finance has its own application process and eligibility criteria. Don’t assume that an assessment for V12 uses the same terms as Klarna. Employment, credit information and affordability may be relevant to a finance decision, but the requirements depend on the specific agreement. A declined application means that option cannot be used for that order; it doesn’t establish that every finance provider will reach the same decision.
Purchase finance is linked to a specific order and repayment agreement. A credit card may provide ongoing borrowing, while a personal loan is a separate borrowing arrangement. Interest, repayment schedules and eligibility rules vary, so compare the total repayment and due dates rather than choosing by the monthly amount alone.
When applying in the UK, provide accurate details and review the agreement before accepting. Credit checks may ask for addresses where you have lived over the last six years. A return and a credit agreement are separate matters: returns depend on the seller’s terms, while the agreement explains how finance is handled. Read both before ordering and follow the lender’s process if a return is accepted.
How do I qualify for 0% APR finance?
Approval depends on the finance application and the terms shown for your order. We use Klarna to provide interest-free payments on amounts up to £1000, spread over 3 months.
Applying at Checkout
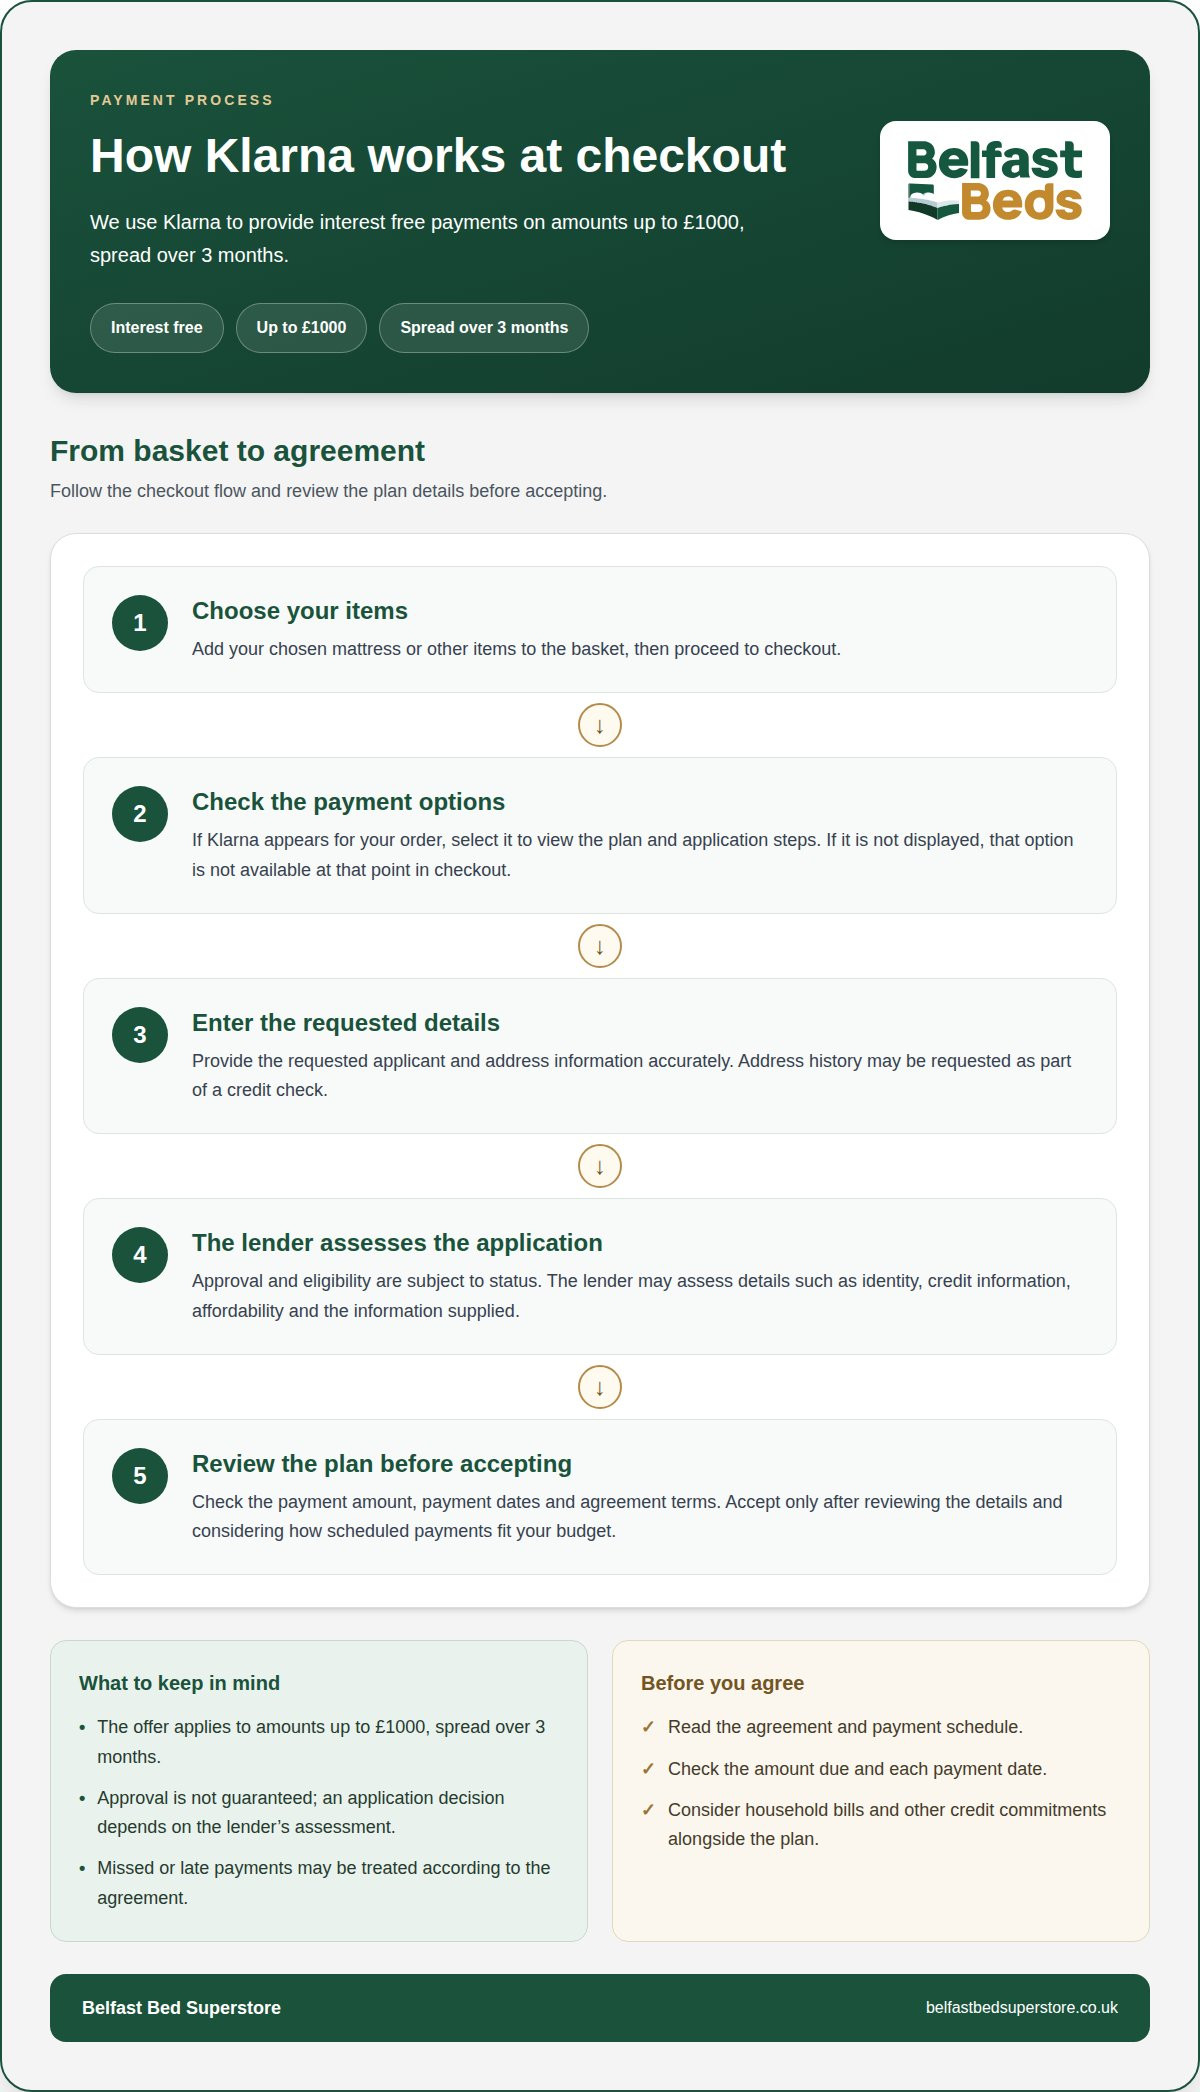
Add your chosen items to the basket and proceed to checkout. If Klarna appears as a payment option, select it to view the available plan and application steps. Enter the requested details accurately, then review the payment dates, amount due and agreement before accepting. The offer is interest free, but approval and eligibility are subject to status.
Applying Online
An online application is completed through the payment flow presented at checkout, rather than by starting a separate loan request. Have your personal and financial details ready, and make sure the information matches your circumstances. Submit the application only after reading the terms. If Klarna isn’t displayed for the order, that payment option isn’t available at that point in the checkout.
For a 0% APR offer, the key distinction is the agreement’s cost of credit. Interest-free payments mean no interest is added under the stated terms, but missed or late payments may be treated according to the agreement. Check the plan details before accepting, including the instalment amount, payment schedule and any conditions. Don’t assume every finance product is 0% APR simply because it lets you spread the cost.
Klarna Financial Services UK Limited is authorised and regulated by the Financial Conduct Authority for regulated consumer credit activities under firm reference number 987889. That status identifies its regulated role; it does not mean every applicant will qualify. A lender assesses the application and may consider credit information, affordability and the details supplied. Employment can form part of an applicant’s financial circumstances, but a permanent job alone does not guarantee approval.
To complete an application, follow the checkout prompts in order:
- Choose the payment option shown for the order.
- Provide the requested applicant and address details, including address history if requested.
- Review the decision and the agreement terms before accepting.
The plan applies to amounts up to £1000, spread over 3 months. Before applying, consider whether the scheduled payments fit your regular budget alongside household bills and other credit commitments. Orders above the stated limit may not fit this particular Klarna arrangement, so the checkout payment options and terms determine what can be selected.
Credit checks and application decisions
A finance application allows the lender to assess the information you provide and decide whether to offer credit. The agreement, repayment schedule and total amount payable matter as much as the monthly figure.
Interest-Bearing Credit and Representative APR
An APR helps show the cost of borrowing, but compare it with the full repayment total. Finance examples can vary by term, deposit and interest rate.
These examples describe different agreements, not a single offer available to every applicant.
Before accepting interest-bearing credit, look beyond the instalment. A longer term can lower each monthly payment while increasing the total cost. Check the APR, deposit, payment dates and total payable in the agreement. A 0% APR offer has no interest within its stated terms, but eligibility and approval still matter.
Lender and Credit Intermediary Information
Check which organisation provides the credit and which acts as an intermediary. Klarna Financial Services UK Limited is authorised and regulated by the Financial Conduct Authority for regulated consumer credit activities under firm reference number 987889. Companies House records Klarna Financial Services UK Limited under company number 14290857.
The lender details identify who provides the credit, but they do not promise approval or explain every term. Before accepting, read the information presented, including who receives your payments, the repayment schedule and the stated consequences of missed payments. Lenders may apply different assessment criteria.
A credit check may form part of the application decision and may request addresses where you have lived over the last six years. Enter accurate details and review the application before submitting it, as incomplete or inconsistent information can affect the assessment.
Approval does not depend on one detail alone. Lenders assess your application and the information available to them; credit history, income, existing commitments and affordability may all be relevant. A decision on one application does not predict another lender’s decision.
Interest-free credit can spread the cost without adding interest under the agreed terms. Our Klarna payments are interest free on amounts up to £1000, spread over 3 months. Keep that arrangement distinct from interest-bearing finance: check the specific checkout agreement for its rate, term and total repayment before choosing.
Can I buy a bed on finance with bad credit?
Your credit history can affect an application, but the lender assesses the details and makes the decision. Before accepting an agreement, compare each repayment example with your budget.
Repayment Examples and Terms
Examples show how the deposit, APR and repayment period affect the monthly payment and total cost.
These figures illustrate different finance agreements, not guaranteed offers for every applicant. For interest-free credit, we use Klarna to provide interest free payments on amounts up to £1000, spread over 3 months. Interest does not apply under those stated terms. For another agreement, check the APR, payment dates and total payable, including when interest applies.
Deposits and Purchase Thresholds
The 12-month example uses a 10% deposit, but that is an example rather than a universal deposit requirement. Review the deposit and financed balance together before choosing a payment option.
There is no single deposit or monthly repayment that applies to every mattress finance plan. The amount depends on the order, deposit, APR and repayment term. Check the agreement to see exactly what you would pay.
Repayment Start and Delivery Conditions
The finance agreement sets out when repayments begin. Do not assume the first payment is due on delivery day: check the schedule for the first due date and payment method. Delivery arrangements and credit repayments are separate, so review both before completing your order.
If you miss a payment, follow the lender’s instructions in the agreement and contact the lender promptly about your account. The agreement explains the process and any consequences. Do not assume a missed instalment will automatically move to a later date.
Before accepting, check the lender, APR, deposit, instalment amounts, number of payments, first payment date and total amount payable. If your application is declined, another lender’s decision is not certain: each application is assessed individually.
Minimum order values for finance options
A finance minimum applies to the amount borrowed, which may differ from the order total. Subtract any deposit from the order total to find the balance to be financed. Compare that balance with the minimum finance amount, then consider whether the repayment option fits your budget.
This is a threshold for the amount financed, not necessarily the minimum price of a mattress or order. A deposit reduces the balance to be financed, so the order total alone does not show whether it meets the minimum.
Our Klarna payments are interest free on amounts up to £1000, spread over 3 months. Don’t assume that meeting one threshold means an order also meets the other. The finance option shown at checkout determines which terms apply.
A deposit can affect whether the remaining balance qualifies. With no deposit, the amount financed may be closer to the order total. Review the deposit, financed amount and repayment schedule together before choosing.
Minimum spend and finance eligibility are separate checks. A qualifying balance does not guarantee approval, and approval does not change the amount or term stated in the agreement. Select the finance option offered for your order, then read its terms carefully. Check the agreement for the payment schedule and any applicable charges rather than assuming every option has the same costs.
- Work out the balance after the deposit.
- Check whether the selected plan falls within its stated limits.
- Read the repayment dates and agreement terms before accepting.
Keep the figures distinct when comparing options. An order outside one arrangement’s limits may have another payment method available at checkout, but its terms depend on the option offered. Meeting a minimum spend is separate from credit approval.
To start with the purchase itself, select a mattress, then review the payment choices and agreement presented at checkout.
Belfast Bed Superstore: Mattress Protectors
Belfast Bed Superstore offers Mattress Protectors alongside Hypnos, Sealy and Relyon Mattresses, giving you options to consider as you plan a more comfortable night’s rest. If you’re weighing a mattress purchase against the payment terms explained above, start by choosing the mattress that suits your support and comfort preferences, then review the payment method and agreement shown at checkout.
A protector is a practical addition to consider with a new mattress. The right choice depends on what you want from your bedding and how you care for your sleep space. You can explore mattress options from Sealy and consider whether a mattress protector fits your needs before making a decision.
Contact Belfast Bed Superstore if you’d like to discuss your mattress and protector options.
Choose a mattress that feels right for your next chapter
If you are still deciding whether to finance a mattress purchase, consider the payment commitment alongside the comfort and support you want. A payment plan is only useful if the mattress suits your needs and home. Think through your priorities, then read the agreement carefully before committing.
Belfast Bed Superstore offers Hypnos, Sealy and Relyon mattresses, with options to explore as you narrow down your choice. Consider the feel and support you prefer, and whether a mattress protector would be a useful addition. Keeping comfort and affordability in view can make the decision clearer.
For a friendly conversation about your mattress options, contact Belfast Bed Superstore. Take the next step at your own pace, with the details you need to choose a more comfortable night’s rest.
Frequently Asked Questions
Who can apply?
You can apply by providing the information requested at checkout, but the lender decides whether to approve the application. Credit history, affordability and the details supplied may be considered. Having a particular job or payment method does not guarantee approval. Enter your information accurately, then read the decision and agreement carefully. If an application is declined, that decision applies to that application and does not establish what another lender would decide.
How does bed and mattress finance work?
Bed and mattress finance lets you pay for an eligible order through a credit agreement instead of paying the full amount upfront. The agreement sets out instalments, payment dates and any interest or other applicable charges. At checkout, select an available payment option and review its terms before accepting. This helps you understand the payment commitment alongside the mattress or bed you have chosen.
Are there any extra fees involved?
Fees depend on the specific agreement, so don’t assume every finance option has identical charges. Check the agreement for any fees, the interest rate and the total amount payable before accepting. We use Klarna to provide interest-free payments for eligible amounts under the stated terms; other credit agreements may have different costs. If a payment is missed, read the lender’s instructions to understand how the agreement handles it.
Are there limits on how much I can spend?
Yes, finance options can have both minimum and maximum amounts. The Klarna arrangement we use provides interest-free payments on amounts up to £1000, spread over 3 months. These limits apply to the amount being financed, so a deposit can change whether the remaining balance fits. The checkout will show which options apply to your order.
Can you buy a mattress on finance in the UK?
Yes, mattress finance is available in the UK through payment options such as the Klarna arrangement we use. Eligible amounts up to £1000 can be paid interest free, spread over 3 months. You’ll need to apply through the payment flow and review the lender’s agreement before accepting. The finance decision and the terms offered depend on the application and the details provided at checkout.
Which UK mattress retailers offer finance or buy now pay later?
We offer payment options for eligible purchases, including Klarna interest-free payments. We also sell Hypnos, Sealy and Relyon Mattresses, so you can consider the mattress and payment choice together. Available payment methods and terms are presented during checkout. Review the option shown for your order and its agreement before proceeding, since payment plans and eligibility can differ between purchases and providers.
What interest rates and fees apply to mattress finance?
The rate and fees depend on the finance agreement you select. The Klarna payments we provide are interest free within the stated terms, while other finance agreements may charge interest. For illustration, one available example lists a representative APR of 11.9%; that figure isn’t a universal rate for mattress finance. Check the agreement’s APR, any fees and total payable before accepting an offer.
How do you apply for mattress finance in the UK?
Choose a mattress and add it to your order, then continue to checkout. Select an available finance option, provide the requested applicant details and submit the application. Read the lender’s decision and agreement before accepting, paying particular attention to instalment dates and the total repayment. For a mattress purchase in the UK, apply through the checkout process.